

Residential roof replacement
Covered under most homeowner policies when hail causes functional damage. RCV policies pay full replacement cost; ACV policies depreciate based on age.
Generally covered
Coverage depends on your policy type, your property's condition, and how well the damage is documented. Here's how each component is typically treated.
Covered under most homeowner policies when hail causes functional damage. RCV policies pay full replacement cost; ACV policies depreciate based on age.
Covered when functionally damaged. The key battle is whether insurers must match existing siding — in many states they must, requiring full replacement even for partial damage.
Outdoor units damaged by hail are covered — but insurers frequently skip them during inspections. We ensure every component is documented and included.
Commercial policies vary widely. We navigate the complexity of commercial policies to ensure roofing, equipment, inventory, and business interruption are all properly claimed.
Water damage resulting from a hail-compromised roof is a covered consequence of the hail event. Insurers try to treat it as a separate claim — we connect the dots.
Some policies include cosmetic damage exclusions. We analyze your policy language to determine what actually qualifies as cosmetic vs. functional damage — and fight the designation when it's wrong.
Hail claims are among the most systematically underpaid in the industry. Here are the tactics insurers use most — and how we counter each one.
Calling damage cosmetic severely limits your settlement — even when hail has compromised the waterproofing and structural integrity of your roof. We document functional impairment to counter this.
Insurers push to patch damaged sections rather than replace. When matching materials don't exist or patching compromises performance, replacement is warranted — and we fight for it.
Roof age is used to depreciate claim values by 10–50% or more. Under a replacement cost value policy, you're entitled to 100% of replacement once repairs are complete — regardless of roof age.
If you didn't report the damage immediately, insurers use that delay to question whether the damage is from the hail event or prior wear. We establish the causal connection and timeline.
Insurer inspections focus on the roof and miss gutters, AC units, screens, and siding. We inspect everything and ensure every hail-damaged component is included in your claim.
Settling at actual cash value — depreciated — rather than full replacement cost is a common tactic that can reduce payouts by thousands of dollars.
Industry Insights
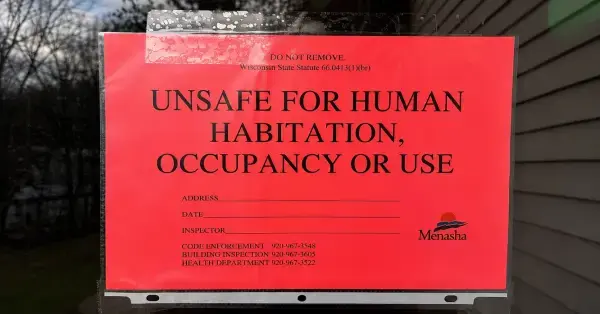
After a tornado or severe storm, learn what red, yellow, and green placards mean, what to do next, and how they may affect your insurance claim.
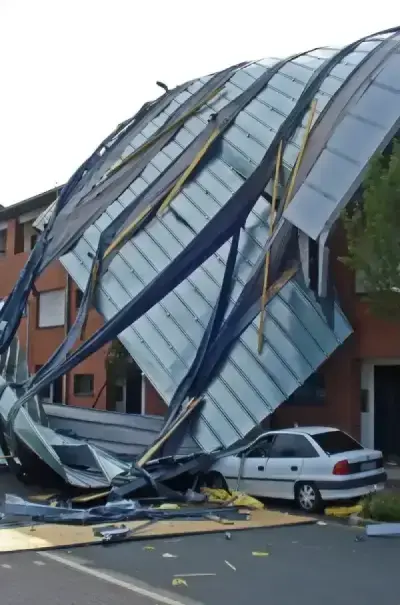
A confirmed tornado hit Menasha, Appleton on July 27, 2026. Miller Public Adjusters helping local homeowners document damage and fight lowball settlements.
Insurance documents are often filled with confusing jargon. Our free glossary explains important terms in simple, plain language — helping you understand your p…
When a fire, tornado, or other covered loss destroys your home, you're expected to list everything you owned -including its age, condition, and value. Our free …
Learn how buildings are built, damaged, and rebuilt to better assess and calculate the full value of your property loss.
A licensed public adjuster helps you deal with your insurance company and fights for a fair payout. Choose the...
Free Claim Review
Start with a free review — we'll dig into your claim, explain your options, and let you know if and how we can help. No obligation, no pressure.


